The Classic Cocktails You Know by Heart Still Have a Few Secrets Left to Give

Classic cocktails can feel fixed in stone, but most of them are anything but. The deeper you look at a Martini, Old Fashioned, Negroni, or Daiquiri, the more you see a set of flexible templates that still shape how drinks are mixed at home and in bars.

Why the “classic” label can be misleading

A classic cocktail usually survives because it is simple enough to remember and flexible enough to keep evolving. The Oxford Companion to Spirits & Cocktails traces the cocktail itself to the early formula of spirits, sugar, bitters, and water, then follows how later drinks stretched that idea with citrus, fortified wine, and liqueurs. That helps explain why so many familiar orders still spark debate over what counts as the standard version.

The Old Fashioned is a strong example. According to the Oxford entry on the drink, the Old-Fashioned Whisky Cocktail became widely popular and later picked up extra embellishments before the modern cocktail revival pushed many bartenders back toward earlier builds. That history explains why one bar may lean minimalist while another still treats fruit and sweetness as part of the drink’s personality.

The Martini is even less settled than its reputation suggests. The Oxford Companion notes that its precise origin remains hard to pin down, and that the drink changed repeatedly across the 20th century, becoming drier, then spawning versions with vodka, olive brine, and service on the rocks. For home cooks and home bartenders, that means “classic” often describes a family of drinks, not a single frozen recipe.

Four standards that still teach technique

The Daiquiri looks almost too basic to hide any surprises, which is exactly why it remains such a revealing drink. Bacardí’s historical material credits Jennings Stockton Cox with creating the Bacardí Daiquiri in Cuba with rum, fresh lime juice, sugar, and ice, and the brand still presents that simple structure as the traditional form. WSET also points to the Daiquiri as a template drink, noting that its three main ingredients put the rum at the center.

The Negroni offers a different lesson, one about balance through equal parts. Campari dates the drink to Florence in 1919, while the Oxford Companion says its broad history is clear even if part of the timeline remains patchy, and notes its postwar rise as a signature of Italian café culture. Equal parts gin, Campari, and sweet vermouth sound rigid, but small choices in gin style, vermouth freshness, and orange garnish can make the drink read sharper, softer, or more aromatic.

The Martini and Old Fashioned teach restraint. With the Martini, a shift in vermouth ratio can move the drink from severe to inviting in one pour. With the Old Fashioned, sugar level, bitters choice, and dilution matter more than extra ingredients, which is why these drinks still function as quiet tests of technique.

What this means for a home bar

For a home setup, the secret is not chasing novelty first. It is learning how a few durable formulas behave in the glass. The current Drinks International cocktail report shows that classic drinks still dominate global bar rankings, with the Negroni, Martini, and Old Fashioned remaining central reference points for bartenders. That staying power reflects how useful these drinks are for teaching proportion and texture.

A practical way to learn them is to change one variable at a time. Try a Daiquiri with the same rum but a slightly different sugar level, or compare a Negroni made with freshly opened vermouth against one from a bottle that has lingered too long in the refrigerator. A Martini built wetter than expected can show how much aroma vermouth contributes, while an Old Fashioned stirred a bit longer will reveal how dilution softens whiskey and bitters.

That is the quiet secret these classics still give up. They are not just old recipes preserved for nostalgia. They are working kitchen and bar lessons, compact enough to memorize, but open enough to keep teaching every time you mix one.
One Reposado Just Outshined the Entire Field at a Major Spirits Competition

El Tesoro Reposado Tequila has been named the 2026 Tequila Trophy winner by the International Wine & Spirit Competition, or IWSC. That matters for readers stocking a home bar because the trophy is IWSC’s top tequila recognition in this year’s spirits judging.

What won, and which competition it actually came from

The key editorial point is simple: this award belongs to El Tesoro Reposado in the IWSC, not to El Tequileño Sassenach Select in the Tequila & Mezcal Masters. The source notes provided with this assignment flagged that mismatch, and the official IWSC winners page backs up the El Tesoro result.

IWSC lists the 2026 Tequila Trophy winner as Reposado Tequila from El Tesoro, from Jalisco, Mexico. In a separate IWSC news post published last month, the organization said El Tesoro Reposado Tequila took the Tequila Trophy during its 2026 Spirits Judging. That same post placed the tequila alongside other category trophy winners across spirits, showing it was part of IWSC’s broader annual awards slate.

This is important because spirits competitions can sound similar while recognizing different products under different judging systems. In this case, the supplied notes correctly separated two real award stories that should not be blended into one headline or article.

Why the distinction matters for shoppers and editors

For readers, the practical takeaway is that award language should be read carefully. A trophy win at IWSC is not the same as a Master medal or a Taste Master title from The Spirits Business’ Tequila & Mezcal Masters, even if both honors involve high profile agave judging in 2026.

The Spirits Business reported in April 2026 that El Tequileño Sassenach Select earned both a Master medal and the Tequila Taste Master title in that competition. That means El Tequileño did have a notable 2026 competition result, but it came from a different organizer and a different set of awards than the one tied to El Tesoro.

For editors, this is the kind of mix-up that can create a misleading story even when each underlying fact is true on its own. The cleaner and better supported article is the one focused on El Tesoro’s IWSC trophy, because that result is confirmed on the competition’s official website and repeated in IWSC’s own announcement.

What the award signals, and what it does not

An IWSC trophy is best read as a judging result, not as a guarantee that every drinker will rank the bottle the same way. Still, the award can be useful shorthand for shoppers who want a starting point when comparing reposado tequilas for sipping, gifting, or building a margarita or tequila old fashioned at home.

IWSC said its spirits trophies recognize the highest-performing individual spirits from the year’s competition. On the 2026 trophy list, El Tesoro appears as the tequila winner, while other categories such as mezcal, vodka, and rum also have separate trophy recipients. That structure helps explain why this result stands out within its category.

What cannot be cleanly confirmed from the readable official IWSC pages available here is the specific 96 out of 100 score mentioned in the supplied notes. Because of that, the safest framing is that El Tesoro Reposado won the 2026 IWSC Tequila Trophy, a verified result on the official competition site, and that any separate score claim should be checked against the original article or award detail page before publication.

Counting Down to December: Which Grocery Chain Fills the Calendar Best?

Aldi

Aldi has the clearest, broadest grocery Advent calendar lineup confirmed for the 2026 holiday season. The chain said on October 30 that more than 25 calendars would reach stores starting November 4, giving shoppers a mix of food, drink, baking, pet, and gift-focused options to count down to December.

Aldi has the widest confirmed grocery lineup

Aldi’s case starts with scale. In its official 2026 announcement, the grocer said this year’s assortment includes more than 25 Advent calendars, which it described as its largest variety since the program began. The company also said the assortment expands into new categories including beauty, baking, stationery, magnetic building toys, non-chocolate candy, and Aldi-branded merchandise.

For grocery shoppers, the food and drink options remain the main draw. Aldi said returning favorites include the Wine Advent Calendar at $59.99, the Emporium Selection Advent Cheese Calendar at $16.99, the Barissimo Coffee and Cocoa Advent Calendar at $16.99, Burman’s Hot Sauce Advent Calendar at $14.99, and the Choceur Kids Advent Calendar at $1.99. The company’s holiday calendar page also lists the Choceur Kids Blue, Green, and Red Advent Calendars at $1.99 each.

Aldi also tied some of those calendars directly to kitchen use. The company said its refreshed wine and cheese calendars are designed to be enjoyed together, with each day’s wine intentionally paired with a complementary cheese. Aldi gave one example pairing, Chardonnay-Fiano with Herb & Garlic Gouda, which helps explain why these calendars may appeal to shoppers looking for easy holiday tasting ideas instead of just candy behind each door.

Trader Joe’s offers less public detail this season

Trader Joe’s does have Advent products on its website, but the public picture is much narrower. Its product page for the Milk Chocolate Advent Calendar lists a price of $1.49 for a 1.76 oz calendar and describes the item as a limited-time seasonal product with 24 chocolates behind the windows. That keeps Trader Joe’s in the holiday countdown conversation, especially for shoppers who want a simple, low-cost classic.

The chain also lists pet-themed calendars online. Trader Joe’s pet category page shows an Advent Calendar for Dogs and an Advent Calendar for Cats, with the cat version priced at $7.99. At the same time, Trader Joe’s notes on its site that not every product is represented online and tells shoppers that the best place to get product information is their neighborhood store.

That caveat matters when comparing chains. Based on what is publicly confirmed and readable right now, Trader Joe’s does not offer the same level of official, centralized detail as Aldi for 2026 grocery Advent shopping. That does not mean Trader Joe’s has a weak holiday assortment in stores, only that Aldi has provided more complete, checkable information for shoppers deciding where to start.

What this means for shoppers filling a December calendar

If the goal is variety backed by confirmed pricing and timing, Aldi fills the calendar best this season. The chain has an announced start date of November 4, a published range beginning at $1.99, and named options that cover chocolate, cheese, wine, coffee and cocoa, and hot sauce. That makes planning easier for anyone building a family countdown, a hostess gift bundle, or a food-centered December tradition.

Trader Joe’s still looks competitive for shoppers who want an inexpensive chocolate countdown or pet-themed treats. Its $1.49 Milk Chocolate Advent Calendar undercuts Aldi’s $1.99 Choceur Kids calendars on posted price, at least for the products currently shown online. But a single low-priced chocolate option is different from a fully mapped holiday calendar program.

So which grocery chain fills the calendar best right now. On confirmed public information, Aldi wins on range, specificity, and food-focused variety. For shoppers who want the broadest one-stop Advent selection with clear pricing before December begins, Aldi has made the strongest documented case.

Before Your Next Grocery Run, Five Facts About Meat Prices Could Change How You Shop

Meat prices can make a routine grocery trip feel unpredictable. One week chicken looks steady, the next week ground beef is suddenly harder to justify. A closer look at the market shows why smart shoppers should pay attention before they fill the cart.

Beef prices are rising faster than many shoppers realize

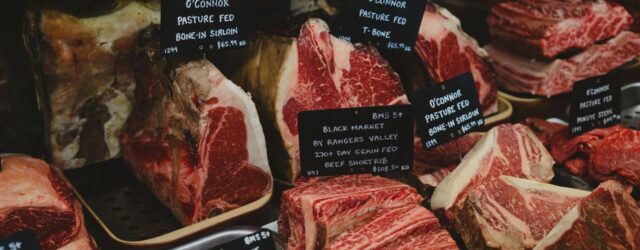
The biggest pricing story in the meat case is still beef. USDA’s latest Food Price Outlook says beef and veal prices are forecast to rise 8.7% in 2026, far above pork at 1.0% and poultry at 1.2%. That makes beef one of the fastest-rising grocery categories in a year when overall food-at-home inflation is expected to be much milder, at 2.3%.

Recent inflation data show that the pressure has not faded. The Bureau of Labor Statistics reported that the meats, poultry, fish, and eggs index rose 0.5% in October 2026, while the beef index alone climbed 0.9% for the month. According to AP, beef prices had already jumped nearly 14% in the first half of this year, which helps explain why many households feel like steak and even burgers have become occasional purchases rather than weekly staples.

That gap matters because consumers do not experience inflation evenly. A family that buys a lot of beef will feel food inflation more sharply than a household centered on chicken, beans, or eggs. It also means the meat aisle now rewards flexibility: choosing chuck over ribeye, family packs over smaller trays, or a beef-and-turkey blend for burgers can produce real savings without changing the whole meal plan.

Cattle inventory headlines can be misleading without the details

One of the easiest mistakes is assuming that a cattle inventory report tells a simple story of shortage or abundance. The July 24 USDA cattle report actually showed total cattle and calves at 94.2 million head, slightly above the 94.0 million a year earlier. So the broad national inventory did not fall. That is an important correction for anyone trying to understand why beef remains expensive.

The more meaningful numbers were deeper in the report. USDA said beef cows totaled 28.5 million, down 1%, and the calf crop came in at 32.5 million, down 2%. At the same time, cattle on feed rose 2% to 13.2 million. In other words, there are still animals moving through the system now, but the breeding base that drives future beef supplies remains tighter.

USDA’s Economic Research Service has been explicit about the result: federally inspected beef production has been lower in most months of 2026 than in the same months of 2025, and it is expected to stay below year-ago levels through the end of the year. For shoppers, that means today’s prices are not just a temporary supermarket quirk. The tighter beef cow herd and smaller calf crop suggest elevated prices can linger even when one headline number appears stable.

The best shopping strategy may be switching proteins more often

When beef gets expensive, shoppers rarely stop buying meat altogether. They substitute. USDA’s October livestock outlook said broiler consumption is expected to rise in 2026 partly because consumers are moving away from high-priced beef and toward chicken for price reasons. That shift is one of the clearest signals in today’s meat market: price-sensitive households are actively reshaping demand.

Pork also looks relatively calmer than beef. USDA forecasts pork prices to rise just 1.0% this year, and September retail pork prices were down 0.7% from a year earlier. Chicken is also projected to post only modest price growth. Those smaller increases give shoppers room to rethink the meal plan, especially for tacos, stir-fries, sandwiches, pasta dishes, and sheet-pan dinners where the protein can change without changing the entire recipe.

The practical takeaway is not to abandon beef, but to buy it more strategically. Save beef for meals where its flavor really carries the dish, then lean on chicken or pork for everyday cooking. If prices remain on their current path, the shoppers who compare proteins rather than fixate on one category will be the ones who keep both their dinners and their budgets under better control.

Fifteen Edible Plants Most Gardeners Have Never Heard Of Could Change Your Backyard

Most backyard gardens repeat the same short list of crops year after year. Yet some of the most useful edibles are still hiding in plain sight, prized by plant collectors, permaculture growers, and regional food historians rather than mainstream gardeners.

What makes these plants so compelling is not novelty alone. Many bring perennial growth, unusual flavors, ornamental appeal, or climate adaptability that can make a home garden more productive and more resilient.

The overlooked edible plants worth knowing

Sea kale, Good King Henry, skirret, sorrel, miner’s lettuce, and garlic chives all deserve wider attention because they blur the line between ornamental and edible gardening. The Royal Horticultural Society describes sea kale as a robust herbaceous perennial with blue-green leaves and white flowers, while Good King Henry is noted as an edible perennial with leaves used much like spinach. That combination of beauty and repeated harvest is exactly why experienced gardeners value them.

Skirret is another rediscovered crop with deep roots in European kitchen gardens. UF/IFAS describes it as a sweet-rooted perennial in the carrot family, grown for white roots that are typically boiled, stewed, or roasted. Sorrel earns its place for a different reason: its lemony bite wakes up soups, sauces, and salads when lettuce feels flat. Miner’s lettuce, documented by the USDA Forest Service as edible raw or cooked, is especially valuable as an early-season green and a good source of vitamin C.

Then there are the plants that act like flavor insurance in the garden. Garlic chives produce edible leaves and flowers with a gentler garlic-onion note than bulb garlic, and they fit easily into borders, herb beds, and containers. Daylily also appears on many adventurous edible lists, but it needs caution: Iowa State Extension notes that young foliage, buds, and flowers can be eaten only from unsprayed plants and only when the plant is correctly identified. That distinction matters more than novelty ever will.

The tubers and roots that can outproduce familiar vegetables

If most gardeners experimented with unusual roots just once, sunchokes, groundnut, oca, mashua, yacon, and crosnes might become staples. Jerusalem artichokes, also called sunchokes, produce crisp, nutty tubers, but extension sources warn they spread aggressively. North Carolina Cooperative Extension notes they can form colonies, and gardeners who leave even small tubers behind should expect a vigorous return.

Groundnut, or Apios americana, offers a very different habit. North Carolina Extension describes it as a native perennial vine with large edible tubers, making it attractive to gardeners who want food crops that also climb and flower. Oca, identified by the RHS as a sprawling perennial with edible fleshy tubers, brings color and novelty as well as yield. Mashua, another Andean crop highlighted by the RHS, is grown for edible tubers with a peppery flavor that mellows after cooking.

Yacon may be the most commercially intriguing of the group. UF/IFAS identifies it as a tuberous root crop native to the Andean region of South America, with sweet roots often compared to apples and pears. Crosnes, also sold as Chinese artichokes, add a delicate, knobby tuber prized by chefs. Together, these plants show that the future of the backyard garden may look less like a standard vegetable row and more like a living pantry of diverse underground crops.

The safety lessons and smart planting strategies gardeners should not ignore

Unusual edibles reward curiosity, but they also punish carelessness. Camas is the clearest example. While edible camas has a long history as a traditional food, USDA and Oregon State University materials warn that poisonous death camas can be mistaken for it, and OSU notes that human poisonings have been reported from mistaken identification. In practical terms, that means camas is not a beginner foraging or casual bulb-sharing plant.

Prickly pear is safer but still calls for informed handling. Its fruits and pads are edible when properly prepared, yet the spines and tiny glochids require careful removal before the plant reaches the kitchen. Even familiar-looking plants can have limits. Daylily must be pesticide-free and correctly identified, and gardeners should remember that “edible” does not mean every part of every plant is safe in every condition.

The real promise of these 15 plants is strategic, not trendy. A backyard that includes perennial greens, climbing native tubers, drought-tolerant succulents, and cool-season salad plants spreads harvests across more months and reduces dependence on one or two fragile crops. For gardeners willing to learn the plants well, these underused edibles can genuinely change both the flavor and function of the home landscape.

Six Fast Food Chains Went Up Against Each Other in One State, and Locals Already Have Favorites

North Carolina is becoming an unusually busy proving ground for fast-food growth. In a single state, national arrivals and entrenched Southern brands are now competing more directly for the same drive-thru traffic.

That makes for a compelling rivalry, but the evidence points to expansion and early buzz, not a documented scoreboard of local winners.

A crowded field is taking shape across the state

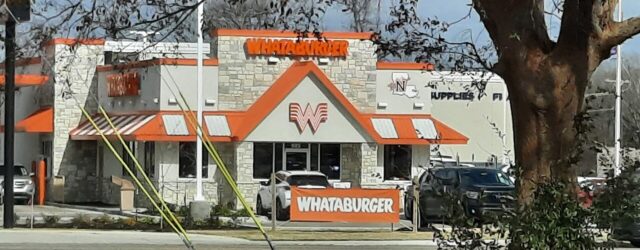
The most visible newcomer is Whataburger, which opened its first North Carolina restaurant in Gastonia on May 29, 2025, according to company materials and local reporting. Whataburger’s own press information says the Gastonia opening made North Carolina its 17th state, giving the Texas-born chain a symbolic foothold in one of the South’s most closely watched restaurant markets. Local coverage also showed strong opening-day interest, including customers eager enough to turn the debut into an event.

That attention matters because North Carolina is not an empty market waiting for discovery. It is already home turf for Bojangles, the Charlotte-founded chicken-and-biscuit chain that still leans heavily on its Carolina identity while expanding nationally. Bojangles describes itself as Carolina-born, and industry reporting has shown the brand continuing to add stores even as it modernizes operations and pushes into new territories.

Other challengers are moving in as well. Raising Cane’s announced its first Rocky Mount restaurant would open on August 3, 2026, marking a fresh entry into that market. Del Taco’s North Carolina footprint remains small but real, with state location listings showing restaurants in Durham and Kernersville. Smashburger has also expanded its presence, with company and trade reporting indicating four open or coming-soon locations in North Carolina, including Charlotte, Durham and Huntersville.

Why North Carolina is such a valuable test market

North Carolina offers a mix that chains prize: fast-growing suburbs, college markets, commuter corridors and a strong drive-thru culture. For restaurant operators, that creates a useful real-world laboratory where breakfast, lunch, dinner and late-night demand can all look different from one city to the next. A chain that works in Charlotte may still need a different playbook in Rocky Mount or the Triad.

The home-state advantage is strongest for Bojangles and Cook Out, though they use it differently. Bojangles competes through breakfast credibility, biscuit heritage and a long-established regional identity. Cook Out, while more private and less expansion-focused in public messaging, has built a loyal following around broad menus, late hours and value positioning that resonate especially well with students and younger drivers.

Newer or newer-to-the-state competitors are approaching the market with sharper specialization. Raising Cane’s centers almost everything on chicken fingers, fries, toast and sauce, a menu discipline that has helped it scale nationally. Whataburger sells familiarity with a Texas accent, while Smashburger and Del Taco bring formats that can appeal to diners looking for something outside the standard burger-or-biscuit routine.

That variety is why sweeping claims about favorites should be handled carefully. There is evidence of curiosity, openings and expansion pipelines. There is not, at least from the reporting currently available, a rigorous statewide ranking proving that locals have already settled on clear winners and losers.

What the competition may mean for diners and chains

For consumers, the immediate effect is simple: more choice and more direct comparisons. When six recognizable chains cluster in the same state, diners begin to weigh convenience, consistency, speed and price with unusual intensity. A breakfast biscuit run, a post-game burger stop and a chicken-finger dinner are no longer separate habits; they are overlapping decisions.

For chains, that raises the stakes on execution. Industry reporting has highlighted Bojangles’ efforts to update store design and drive-thru systems, a sign that legacy brands understand nostalgia alone is not enough. Newcomers, meanwhile, have to convert opening-week crowds into repeat business, which is far harder than generating social-media excitement around a launch.

The smartest conclusion is not that North Carolina has already crowned champions. It is that the state has become a meaningful contest zone where brand identity, operational speed and local adaptation will matter more than hype. If clear favorites do emerge, they will need to be demonstrated through traffic data, sales trends, survey work or sustained customer behavior, not just a packed opening day.

Every Generation Packs Its Own Road Trip Snacks, and the Differences Might Surprise You

The road trip snack bag has become a small cultural archive. What riders toss into the cup holder, glove box, or cooler often reveals how they travel, what they value, and who they expect to feed along the way.

That matters more than it might seem. As road travel remains a major part of the American vacation mix, snack choices are telling a generational story in real time.

Why road trip snacks reveal more than taste

Road trips still hold a powerful place in U.S. travel culture, even as travel habits evolve. Deloitte’s 2026 Summer Travel Survey found that 66% of surveyed travelers planned to take a road trip, a sign that driving vacations remain mainstream despite higher travel costs. RVshare’s 2026 Travel Trend Report also found that more than one-third of travelers already had RV vacations planned for the year, with Millennials leading that interest. Together, those findings help explain why portable, easy-to-share food remains such a central part of trip planning.

Snacks matter on the road because they solve several problems at once. They reduce stops, help travelers control spending, and make long drives feel more relaxed and personal. In family travel especially, the snack bag functions like a peace treaty: one parent wants convenience, one passenger wants indulgence, and someone in the back seat wants a familiar favorite immediately.

Older snack research helps frame the broader shift. In the fifth annual U.S. Snack Index from Frito-Lay and Quaker, reported by NACS in December 2023, 55% of Americans said protein was the most important nutritional attribute in snacks, while 79% said protein should take center stage, especially for people on the go. That does not prove road trippers specifically are prioritizing protein today, but it does show how strongly convenience snacking has been shaped by satiety and function.

Gen Z and Millennials want snacks with personality

Younger travelers tend to treat snacks as part fuel, part self-expression. A 2025 Kellanova survey of 2,000 U.S. adults who had recently gone on or planned a road trip found that Cheez-It and Pringles ranked among favorite road trip brands across generations, but Gen Z was most likely to reach for bolder flavors. That fits a wider food culture in which novelty, heat, tang, and limited-edition appeal carry real weight.

Millennials approach the snack stash somewhat differently. According to Kellanova, they were more likely than other generations to choose tangy flavors, but they were also especially focused on keeping the whole family happy. That combination makes sense for a generation now occupying peak family-travel years: they may want adventurous flavors for themselves, yet still buy broadly acceptable crackers, fruit snacks, bars, and shareable chips for everyone else.

Instacart’s Harris Poll-backed celebration snack research adds another layer. Its 2025 findings showed younger adults over 21 leaning harder into convenience and group-oriented stocking behavior, while Millennials over-indexed on kid-friendly and family-use items such as squeeze snack pouches. On the road, that translates into a mixed basket: something nostalgic, something practical, and at least one snack chosen because it keeps the back seat quiet for another 90 miles.

Gen X and Boomers still trust the classics

Gen X often sits in the middle of the snack spectrum, balancing practicality with a little indulgence. Kellanova’s road trip survey found that Gen X, like Boomers, leaned toward salty and sweet flavors and tended to keep things simpler in how they traveled. That preference shows up in the kinds of snacks that travel well without much planning: pretzels, nut mixes, sandwich crackers, jerky, and familiar potato chips that do not require refrigeration or explanation.

Boomers, meanwhile, continue to favor reliability over experimentation. For many older travelers, a road trip snack is supposed to be recognizable, tidy, and easy to portion. That usually means classic combinations rather than flavor-chasing: peanuts and raisins, cheese crackers, cookies, apples, or a carefully packed cooler with sandwiches and canned drinks. The appeal is not just habit. It is predictability, value, and the comfort of knowing exactly what will satisfy hunger between stops.

The surprise is that these generational differences are not really about age alone. They reflect life stage, travel party size, health priorities, and the emotional role food plays in the car. Gen Z may snack for stimulation, Millennials for household harmony, Gen X for efficiency, and Boomers for comfort. Put them all in separate vehicles heading down the same interstate, and the snack choices will look different, but the purpose is identical: make the miles easier, cheaper, and a little more memorable.

Americans Named the Foreign Grocery Stores Worth Driving Across the Border For

A border crossing can turn an ordinary grocery trip into a mission. For some Americans, the payoff is access to store brands, bakery counters, and prepared foods that feel meaningfully different from what they can buy at home.

Why Canadian chains keep ending up on U.S. shoppers’ radar

Canada’s grocery market is unusually concentrated, which helps explain why certain banners become destination names for cross-border shoppers. A USDA Foreign Agricultural Service report said five major retailers controlled approximately 75 percent of Canada’s food and beverage retail market in 2023, while a later USDA market summary described five retailers accounting for more than 65 percent of grocery sales in 2024. That kind of scale gives major chains the buying power and private-label reach to build recognizable experiences across provinces.

Loblaw remains the clearest example. Its 2025 annual report says the company operates more than 2,800 stores, pharmacies, and clinics across Canada, but that figure should not be described as all grocery stores. Within its supermarket division, the company lists banners that many U.S. visitors know by sight or reputation, including Real Canadian Superstore and No Frills, along with T&T, the Asian grocer that has become one of the most talked-about retail exports from Canada.

Metro is another major player with a strong regional identity. The company’s 2025 annual reporting says it operates or services 1,006 food stores, with banners including Metro, Super C, Food Basics, and Adonis. For Americans crossing into Quebec or Ontario, that matters because banner differences shape what they actually encounter, from discount assortments to stronger Mediterranean or specialty offerings.

T&T adds another layer to the appeal because it has proven there was already pent-up U.S. demand for the format. The chain opened its first U.S. store in Bellevue, Washington, on December 5, 2024, and later said Bellevue and Lynnwood both won recognition in Seattle-area readers’ choice awards in 2026. The company has also said Bellevue was chosen in part because shoppers from the Seattle area were already driving to its Richmond, British Columbia, store.

In Mexico, scale matters, but format matters even more

Mexico’s best-known grocery names are not a single uniform experience. That is especially true at Soriana, whose store locator and corporate materials show multiple formats, including Híper, Mercado, Súper, Express, and City Club. For a U.S. shopper crossing the border, that means the destination value depends heavily on which version of the chain they are actually visiting.

That distinction is important because store counts can quickly become outdated. Soriana reporting has previously circulated higher figures, but its corporate information listed 801 stores as of September 2026, so older totals should not be treated as current. In practical terms, the chain’s footprint is still large enough to make it a central player in Mexican grocery shopping, especially in border states and major urban markets.

Chedraui has a different kind of relevance for Americans because it already operates on both sides of the border. Chedraui USA says it has 383 stores across California, Arizona, Nevada, New Mexico, and Texas. That gives many U.S. shoppers brand familiarity before they ever visit a Mexican branch, even if claims about Mexican stores being categorically better stocked or stronger in bakery execution are harder to verify without direct comparative reporting.

What does hold up factually is that Mexican grocery retail can feel more format-driven and local in its assortments. In chains with broad footprints, hypermarket-style stores, neighborhood supermarkets, warehouse formats, and small express locations can each serve a different mission. For Americans making a special trip, the smartest move is not chasing a logo alone, but targeting the right format in the right city.

What makes a border grocery trip feel worth the miles

The stores Americans talk about most often are usually the ones that combine scale with a sense of discovery. In Canada, that often means a tight mix of private label, prepared foods, and specialty departments inside chains large enough to keep standards consistent. In Mexico, the appeal is often format variety, regional product mix, and the chance to shop a retailer at its domestic center of gravity rather than a U.S. adaptation.

Prepared food has become a major differentiator. T&T’s U.S. announcements have highlighted dim sum displays, noodle counters, sushi bars, street-food stations, and a bakery-deli lineup running into the hundreds of items. That kind of merchandising helps explain why a grocery run can double as a food outing, and why some chains inspire destination behavior instead of routine errand shopping.

Private label also plays a quiet but important role. Large chains in concentrated markets can develop store-brand ecosystems that go well beyond pantry basics, shaping how shoppers perceive value and exclusivity. That does not prove every American thinks a cross-border trip is worthwhile, but it does explain why certain names come up repeatedly whenever shoppers compare what feels distinct abroad.

In the end, the foreign grocery stores worth driving across the border for are not necessarily the biggest ones, but the ones with a clearly different proposition. A massive footprint helps, yet the real draw is a combination of trust, novelty, and food that feels hard to replace back home. That is what turns a supermarket into a destination.

Thousands of Kitchen Appliances Were Pulled Nationwide After Dozens of Reported Injuries

Air Fryer Oven

A large air fryer recall is affecting a countertop appliance many home cooks use for quick dinners, reheating leftovers, and small-batch baking. Gourmia and the U.S. Consumer Product Safety Commission said on November 5, 2026 that about 175,951 air fryer ovens are being recalled because the doors can close unexpectedly while people are taking out hot food.

Which Gourmia air fryer ovens are included

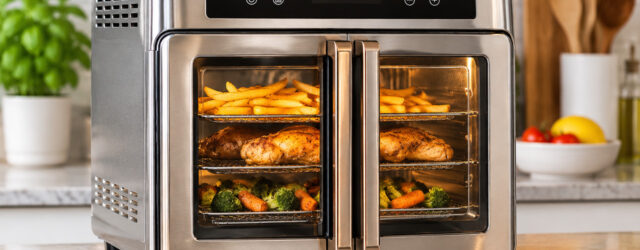
The recall covers Gourmia Stainless Steel Digital 9 Slice Digital Air Fryer Ovens. According to the CPSC, the affected model number is GTF7530 and the UPC code is 810002862779. The recalled ovens are stainless steel and have two spring-loaded glass front French doors with metal handles.

The agency said shoppers can also check a label on the back of the unit for the model number GTF7530 and codes ranging from 3021 to 0126. Those details matter because Gourmia sells other countertop appliances, and this recall is limited to this specific air fryer oven model.

The CPSC said the ovens were sold at Target stores across the country and on Target.com from October 2021 through June 2026. The listed price in the recall notice is about $150. The importer is The Steelstone Group LLC, doing business as Gourmia, of Brooklyn, New York, and the appliances were manufactured in China.

For readers keeping track of official records, the CPSC lists this action as recall number 27-069. This is a consumer product recall, not an FDA or USDA food recall, so there is no FDA recall number or food hazard classification attached to this notice.

Why the appliance was recalled

According to the CPSC, the hazard involves the oven’s doors unexpectedly closing when bumped. That creates a burn risk for people reaching in to remove hot food, trays, or cookware. In a busy kitchen, where cooks are often moving quickly or wearing oven mitts, that kind of door movement can be especially concerning.

Gourmia reported 57 incidents of the oven doors closing unexpectedly when consumers were retrieving food. The CPSC said those reports led to 40 burn injuries involving consumers’ hands or wrists. The recall notice does not list states individually, and instead says the ovens were sold through Target stores nationwide and online.

That distinction matters because some recalls provide store-by-store or state-by-state distribution lists, but this one does not. Based on the official notice, shoppers should identify the product by model number, UPC, and back-of-unit code rather than by where they live or where they usually shop.

The source material supplied with this prompt included general first-aid advice for minor burns, but the official CPSC recall notice focuses on the product hazard and the repair remedy. Because this is a product recall story, the key takeaway for consumers is to stop using the oven and follow the company’s recall instructions.

What shoppers should do next

The CPSC says consumers should stop using the recalled ovens immediately. Gourmia is offering a free repair kit by mail, and the company said the kit includes an added doorstop plus instructions for installation. The recall notice does not direct consumers to return the appliance to Target for a refund.

Instead, consumers are instructed to contact Gourmia directly. The recall notice lists Gourmia’s toll-free number as 888-834-0092, available Monday through Friday from 9 a.m. to 5 p.m. It also says consumers can go to Gourmia’s recall information page through the company website for more details.

For home cooks, the practical concern is simple: if this oven is part of your regular meal routine, check the back label before using it again. If the model number is GTF7530 and the identifying codes match the recall notice, the official guidance is to stop using it until the repair kit is installed.

Air fryer ovens have become weeknight staples because they can toast, roast, and crisp food fast in a small space. That convenience is exactly why a recall like this can affect daily cooking habits, especially ahead of heavy holiday kitchen use.

Ten Ingredients Are Quietly Taking Over Modern Kitchens, and Cooks Who Skip Them May Fall Behind

Modern home cooking is getting sharper, faster, and more flavor-driven. The biggest shifts are not always flashy, but they are unmistakable once you know where to look.

What is changing now is not just taste, but technique. The most influential ingredients in today’s kitchens are compact, versatile, and able to make ordinary food feel current with very little effort.

Flavor concentrates are becoming the new weeknight advantage

The modern pantry is increasingly built around ingredients that do more than one job at once. A spoonful of Calabrian chile can add heat, fruitiness, and richness to tomato sauce, mayo, or roasted vegetables without requiring a full spice blend. The Specialty Food Association flagged Calabrian chile peppers as a rising specialty-food trend, noting their spread into pasta sauces, hot sauces, cured meats, snacks, relishes, and hot honey, a sign that this is no longer a niche import but a broadly useful flavor tool.

That same logic explains the rise of concentrated finishing ingredients like chili crisp, herb pastes, flavored butters, and global sauces. McCormick’s 2026 Flavor Forecast put this shift in plain terms with its “Sauce from Somewhere” theme, arguing that consumers are becoming more fluent in bold regional flavors and are reaching for dips, drizzles, spreads, and sauces to transform routine meals. In practical terms, that means cooks can turn plain eggs, noodles, rice bowls, or grilled chicken into something far more distinctive in seconds.

Vinegar is also being reimagined as an everyday flavor builder rather than a background acid. Whole Foods Market’s 2026 trends report highlighted a “Very Vinegar” wave that ranges from bolder vinaigrettes to fruit-forward and culinary specialty formats. That matters because today’s strongest pantry ingredients are not just seasonings. They are shortcuts to balance, helping home cooks hit salt, fat, heat, and acid quickly enough to cook with more confidence on busy nights.

Fermented, cultured, and preserved staples are gaining new power

Sourdough has moved far beyond the loaf. Whole Foods Market’s 2025 trends report identified “Sourdough Stepped Up” as a breakout pattern, with sourdough showing up in pizza crusts, flatbreads, brownies, crackers, chocolate, and even pasta. The appeal is partly flavor and partly convenience: consumers want the tang and craft cues of fermentation without having to maintain a starter at home. What matters for cooks is that sourdough now signals a broader preference for ingredients with complexity already built in.

Seaweed is following a similar path from specialist aisle to pantry staple. Whole Foods Market’s same 2025 report highlighted plant-based aquatic ingredients, including seaweed, sea moss, duckweed, and agar-agar, reflecting growing interest in marine ingredients as sources of flavor, texture, and nutrition. For home kitchens, seaweed’s advantage is not novelty alone. Nori, kelp seasonings, and seaweed flakes bring salinity and savoriness that can sharpen grains, soups, popcorn, eggs, and seafood with almost no prep.

Preserved fish has also moved decisively into the mainstream conversation. Instacart reported that canned sardines posted 51% year-over-year growth in share of items sold in the first half of 2026 versus the same period in 2025, making tinned fish one of the clearest pantry risers in current grocery data. This is a significant shift because preserved ingredients once treated as backup food are now prized for protein, shelf life, and immediate meal utility.

Protein, fiber, and old-school fats are redefining what counts as useful

If flavor is one half of the new pantry equation, function is the other. Instacart said searches containing the word “protein” rose 12.7% year over year in the first half of 2026, while searches containing “fiber” climbed 26.4%. Cottage cheese increased 10% in share of items sold over the same period, showing how quickly once-unfashionable staples can return when they align with current priorities around satiety, convenience, and versatility.

This helps explain why ingredients like cottage cheese, oats, beans, and seeded add-ins are gaining status. They are adaptable enough to move between breakfast, snacks, sauces, dips, and baking while also fitting the current demand for more nutritionally purposeful food. Whole Foods Market’s 2026 report underscored that momentum by spotlighting fiber-focused products and oats, especially products marketed around prebiotic fiber and everyday digestibility rather than luxury alone.

Even fats are being reevaluated through this lens of practicality and performance. Whole Foods Market’s 2026 trends report singled out beef tallow as a returning ingredient valued for flavor and high-heat cooking. Not every household will adopt it, and it is hardly a universal replacement for olive oil or butter, but its revival says something important about the moment: modern cooks are rewarding ingredients that feel efficient, multi-purpose, and distinctive. The kitchens falling behind are usually not the least expensive or least equipped. They are the ones still stocked for a slower, blander era.